📊 Full opportunity report: Supplier Overcharge Auditor For Restaurant Groups on IdeaNavigator AI — validation score, market gap, and execution plan.

Get movie nights delivered free with Prime
- Fast, free delivery on millions of items
- Prime Video, Amazon Music and more included
- Member-only deals all year
TL;DR
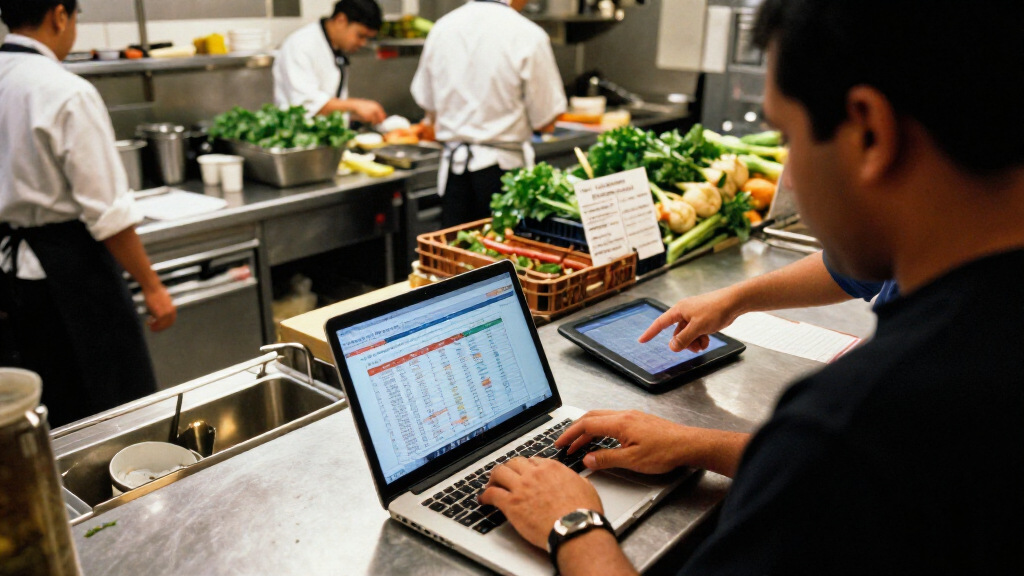
IdeaNavigator AI has outlined a supplier invoice-auditing service for independent restaurant groups, aimed at identifying billing above agreed prices, short shipments charged in full and other discrepancies. The proposal is an unvalidated business concept, not a launched product or a reported recovery program; its suggested next step is a 90-day review of records from three groups.
IdeaNavigator AI has proposed a supplier overcharge-auditing service for independent restaurant groups, designed to compare supplier invoices with agreed prices, purchase orders and delivery records. The concept targets purchasing directors and controllers who manage bills from broadline and specialty food and beverage suppliers, but no product launch, customer results or recovered credits are reported.
The proposed tool would take in invoices through electronic data interchange where available, or through PDF and photo scanning with optical character recognition. It would also use each supplier’s contract or quote sheet and the restaurant group’s order guide. The system would compare the price and quantity ordered, received, billed and agreed for each line item.
It is intended to flag several kinds of potential discrepancy: a billed price above the contracted or quoted amount, cases charged in full despite a short shipment, substitutions billed at a higher price, and week-over-week price changes. The proposed workflow would draft a credit request for each supplier and track it until a credit appears on a later invoice. Those are described functions of a proposed minimum viable product, not capabilities shown to be operating in a commercial service.
The suggested customer would pay a monthly fee per location, with an optional contingency fee tied to recovered credits. To test whether the model is viable, IdeaNavigator AI recommends reviewing 90 days of paid invoices and contracts or quote sheets at three restaurant groups. The test would total documented discrepancies and compare credits with the planned subscription cost per location.
Supplier Overcharge Auditor For Restaurant Groups
IdeaNavigator AI proposes a service to compare supplier bills with agreed prices, orders and delivery records. It is an unvalidated business concept, with no reported launch or recovered credits.
What the proposed tool checks
It would reconcile invoice lines against contracts or quote sheets, purchase orders and delivery records.
Above agreed price
Flag a billed price that exceeds the contracted or quoted amount.
Short shipment
Identify cases charged in full despite a smaller delivery.
Higher-priced replacement
Flag substitutions billed at a higher price and week-over-week price changes.
How a proposed review would work
The suggested test uses paid records to see whether documented recoveries justify the planned fee.
Review 90 days of paid invoices and contracts or quote sheets at three restaurant groups.
Check prices and quantities against orders and delivery records where available.
Pursue supplier credits and track whether they appear on later invoices.
Measure confirmed credits per location against the planned subscription fee.
Where the business case stands
The proposal describes a potential workflow and payment model, but provides no customer or recovery results.
- Monthly subscription fee per location.
- Optional contingency fee tied to recovered credits.
- Draft supplier credit requests and track them to later invoices.
- No product launch or customer trial is reported.
- No measured discrepancy rates or recovered amounts.
- No evidence that savings exceed the service cost.
Checking Supplier Bills Against Margins
The proposal addresses a recurring operational risk: restaurants can lose money when prices, quantities or substitutions on invoices do not match their agreements and deliveries. If staff do not catch discrepancies before payment, the cost can be absorbed into food spending and reduce the margin available to cover labor, rent and other expenses. The concept’s practical value would depend on how often such errors occur and whether suppliers issue credits after receiving a documented request.
Its suggested pricing test also makes the business case measurable. A restaurant group would need to recover enough money, or avoid enough future overbilling, to justify the subscription and the time needed to resolve flagged items. The proposal does not provide actual error rates, recovery totals, customer commitments or evidence that the service saves more than it costs. Those figures would be needed before restaurant operators could judge its financial impact.
The idea is aimed at groups with multiple locations and a high volume of supplier invoices, where manual checking can be difficult to carry out consistently. A tool that reconciles records could make exceptions easier to identify, but it would not by itself confirm that goods were missing or that a supplier owes a credit. That may require delivery records, staff review and a response from the supplier.
Popular right now

Ninja Mega Kitchen System Blender and Food Processor, 1500W, 72-oz Pitcher, 8-Cup Bowl, Black (BL770)

De'Longhi Rivelia Fully Automatic Espresso Machine with Milk Frother, White

iRobot Roomba 105 Combo Robot Vacuum and Mop
As an affiliate, we earn on qualifying purchases.
A Proposed 90-Day Records Test
The concept is framed around a specific buyer: a purchasing director or controller at an independent multi-unit restaurant group purchasing from broadline and specialty food and beverage suppliers. Its stated problem is that groups may process hundreds of supplier invoices each week while agreed prices, delivered quantities and billed amounts are checked across separate records or not matched consistently.
To explain the timing, IdeaNavigator AI cites a USDA Economic Research Service Food Price Outlook dated September 25, 2026. The supplied figures forecast 2026 retail beef and veal prices rising 9.4% and wholesale beef prices rising 8.5%, while food-away-from-home prices are forecast to rise 3.5%. These are forecasts, not confirmed final price changes. The comparison is presented as a reason that supplier price accuracy could matter to restaurant margins when input costs rise faster than menu prices.
The recommended initial test is a 90-day lookback across three restaurant groups, using paid invoices and the relevant contracts or quote sheets. The proposal says to proceed only if documented credits per location clearly exceed the planned subscription fee. No participating groups, test results or decision to proceed are identified.
Pilot Results and Supplier Credits
No commercial launch or customer trial is reported. The proposal does not name a software provider, restaurant group, supplier partner or product release date. It also provides no measured count or value of overcharges, short shipments, substitutions or price changes found in restaurant records.
It remains unclear how the system would establish what was actually received, especially when delivery paperwork is incomplete or a kitchen manager has accepted a substitute. The description does not explain how it would handle different supplier data formats, contract exceptions, taxes, promotions, disputed invoices or errors in scanned documents. It also does not report how suppliers would respond to credit requests or how long a credit would take to appear.
The USDA figures cited are forecasts for 2026, not evidence that restaurant groups have experienced a particular level of supplier overbilling. The proposal offers no baseline for the frequency of invoice discrepancies or expected recovery rates. Its financial case therefore remains a hypothesis until records are reviewed and recoveries are documented.
Measure Recoveries Before Launch
The next step set out in the proposal is a 90-day retrospective review at three restaurant groups. That review would compare paid invoices with supplier contracts or quote sheets and, where possible, order and delivery records. It would total the identified price differences, short-shipped cases billed in full and other documented discrepancies.
The groups would then need to pursue the relevant supplier credits and track whether those credits appear on later invoices. Comparing the confirmed amount recovered per location with the proposed subscription fee would provide an initial test of willingness to pay and potential customer value. IdeaNavigator AI says the project should proceed if documented credits clearly exceed the planned fee; no such test results or launch decision have been announced.
Key Questions
Is the restaurant invoice-auditing service already available?
No launch is reported. The service is presented as a proposed business concept and minimum viable product, not as a confirmed product available to restaurant groups.
What would the proposed tool check?
It would compare supplier invoice lines with agreed prices, purchase orders and delivery quantities, flagging possible overcharges, short shipments billed in full, higher-priced substitutions and price changes between orders.
How would the concept be tested?
The suggested validation is a 90-day lookback at three restaurant groups, comparing paid invoices with contracts or quote sheets and measuring documented credits per location against the planned subscription fee.
What would restaurant groups pay?
The proposed model is a monthly subscription per location, with an optional contingency fee on recovered credits. No actual pricing or customer terms are provided.
Have savings or recovered credits been demonstrated?
No results are reported. The concept does not include measured error rates, recovered-credit totals or evidence that savings would exceed fees.
Source: IdeaNavigator AI